
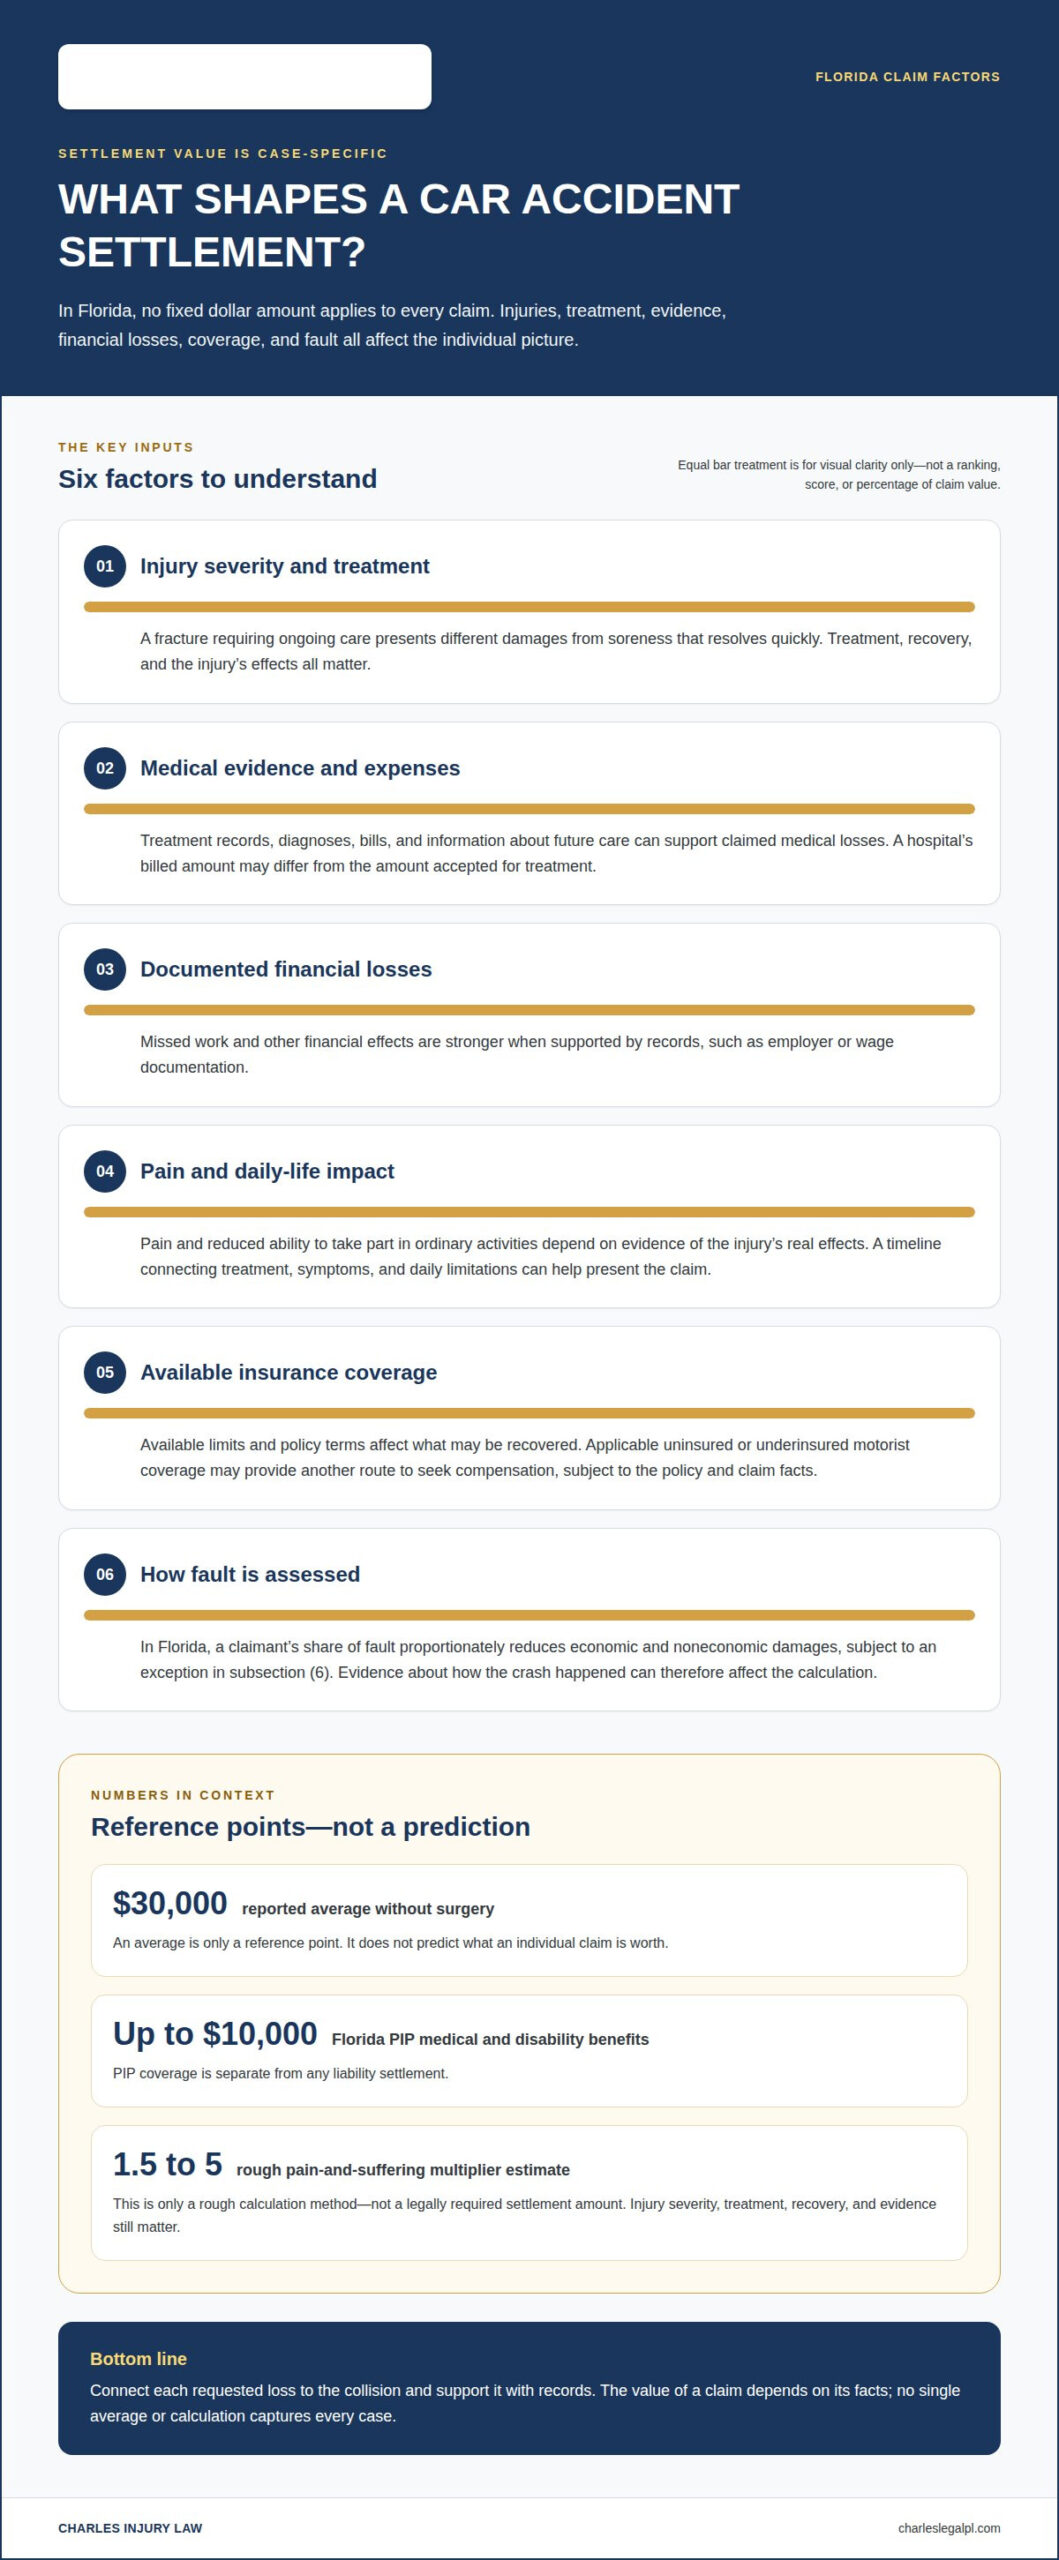
What if a Florida car accident settlement has no fixed dollar amount? The reported average without surgery is $30,000, but the State Farm car accident settlement process turns on the injuries, treatment, evidence, and available coverage in the individual claim. Florida PIP coverage provides up to $10,000 in medical and disability benefits, which is separate from any liability settlement.
It’s understandable to want a clear figure, especially while medical bills and missed work add pressure. But an average is only a reference point, not a prediction of what your claim is worth. Florida’s comparative-fault rule can also affect recovery: according to the Florida Legislature, a claimant’s share of fault proportionately reduces economic and noneconomic damages, subject to an exception in subsection (6).
This article explains how the State Farm car accident settlement process works in Florida, what can affect a settlement, and how negotiations and payment may proceed. It also covers Florida recovery limits and practical steps for understanding the decisions ahead.
Key Takeaways
- Settlement value depends on the injury evidence, treatment, financial losses, available coverage, and how fault is assessed.
- After a written settlement, Florida law generally requires the insurer to tender payment within 20 days; payment may depend on signing a mutually agreeable release.
- A complete demand package can help move negotiations forward by presenting the crash evidence, medical bills, and other documented losses together.
- Negotiations may involve counteroffers or mediation. An early offer is not the only possible outcome, so understand the terms before accepting.
- Organized claim records, including reports, photos, bills, policy information, and rental receipts, can support the claim review.
1. Factors affecting State Farm settlement values
A State Farm settlement has no fixed value for every Florida crash. The claim’s evidence, the injuries, financial losses, available coverage, and fault assessment all matter. A fractured bone requiring ongoing care presents different damages from soreness that resolves quickly. The car accident injury claim should connect each requested loss to the collision.
Medical evidence helps show the injuries and how they affect daily life. Treatment records, diagnoses, bills, and information about future care can support claimed medical losses. A hospital’s billed amount, for example, may differ from the amount accepted for treatment. Insurers may consider the records and payment history when assessing medical expenses.
Lost income and other documented financial effects can also affect a claim’s value. A driver who missed work may support that loss with employer or wage records. Non-economic damages, such as pain and reduced ability to take part in ordinary activities, depend on evidence of the injury’s real impact. A clear timeline linking treatment, symptoms, and daily limitations can help present the claim.
Some estimates use a pain-and-suffering multiplier of 1.5 to 5, but it is only a rough calculation method. It does not set a legally required settlement amount or account for every case detail. The injuries’ severity, treatment, recovery, and supporting evidence still matter. A calculation that ignores those facts may poorly reflect the claim.
Fault can reduce the recoverable amount. According to The Florida Legislature, in Florida, a claimant’s contributory fault proportionately reduces economic and noneconomic damages but does not by itself bar recovery, subject to an exception in subsection (6). The driver’s actions and the evidence about how the crash happened can therefore affect the settlement calculation.
Should I accept a State Farm settlement before completing medical treatment? Usually, avoid settling before you understand your injuries, expected care, and likely recovery. If treatment is ongoing, the full effect on medical expenses, work, and daily activities may not yet be clear. A final settlement may resolve the claims covered by its terms, even if symptoms continue.
Does accepting a State Farm settlement require signing a release, and can I reopen the claim later? Payment may depend on signing a release, and its wording determines which claims it resolves. Don’t assume you can reopen a settled claim later. Understand the terms before accepting.
What happens if the other driver is uninsured or underinsured and I have State Farm coverage? If your policy includes applicable uninsured or underinsured motorist coverage, it may provide another way to seek compensation, subject to the policy terms and claim facts. Available limits, coverage terms, and evidence of losses affect what may be recovered.
2. Deadline for payment after a written settlement
Reaching agreement and receiving funds are separate steps in a Florida insurance claim. According to The Florida Legislature, an insurer must tender payment within 20 days after a written settlement is reached, and payment may be conditioned on signing a mutually agreeable release. The written agreement matters because it records the settlement terms and helps identify when the payment period begins.
A settlement offer is not the same as a completed written settlement. If the parties are still negotiating the amount, or key terms remain unresolved, the payment deadline described above may not have started. For example, a claimant who accepts an amount verbally but has no written agreement should not assume the 20-day period has begun.
The release is another important step. It states which claims the settlement resolves, so its wording should match the agreement before you sign. If it includes terms that differ from the negotiated settlement, address the discrepancy before treating the matter as complete. A signed release can affect your remaining rights after payment, so review its scope carefully.
Once the written settlement and required release are in place, track payment against the agreement’s terms. Keep copies of the signed documents and note when payment is issued. If State Farm says payment is being processed, ask about its status and compare it with the written settlement terms. A vehicle repair claim and an injury claim may involve different documents, so identify which settlement the agreement covers.
Florida Statute 627.4265 provides for interest at 12 percent per year on late settlement payments under the conditions described in the statute. That rule does not mean every delay automatically triggers interest. The terms of the settlement and the statute’s conditions matter. If the payment appears late, preserve the written agreement, release, correspondence, and any payment notices. Those records help clarify the settlement date and the insurer’s actions.
What deadlines and statutes of limitations apply to State Farm accident claims in each state? This section covers Florida, not other states. The 20-day rule concerns payment after a written settlement; it is separate from any deadline for filing a lawsuit, which must be assessed under Florida law for the particular claim.
Don’t let an unclear release or payment delay obscure the agreement. Get help reviewing your settlement documents if the written terms, release, or payment status create uncertainty.
3. Demand packages and settlement timelines
A demand package presents an injury claim in an organized way before negotiations intensify. For a State Farm claim, it can identify the collision, explain why the other driver is responsible, and connect documented losses to the crash. The goal is a clear request supported by relevant records, not a pile of unrelated paperwork. A lawyer can organize the evidence and explain how each item supports the requested settlement.
Useful materials may include the police report, vehicle-damage photographs, medical bills, policy information, and rental receipts. Treatment records and wage documentation can also show how injuries affected health and work. A rental receipt, for example, documents a transportation expense, while repair photographs show visible vehicle damage. A chronology can link the crash, treatment, missed work, and later expenses without unexplained gaps.
How do personal injury attorneys file a car accident claim with State Farm, and what information should clients provide? Lawyers generally notify the insurer, identify the claim, and submit supporting records with a demand explaining liability and losses. Clients can provide crash details, insurance information, the police report, photographs, medical bills, treatment history, wage records, and rental documents. Accurate dates and consistent details help address questions.
Once submitted, the package gives the adjuster information to review and respond to. State Farm may request more information or dispute fault, treatment, or claimed damage. Requests can affect timing, especially when records are incomplete or the medical picture is still developing. A lawyer can respond with relevant evidence and keep negotiations focused on documented losses rather than assumptions.
Settlement timing varies with injury severity, treatment, evidence, and disputes over fault. Most minor injury cases settle within 6 months, while unresolved treatment or difficult liability questions can extend discussions. State Farm does not make a good offer before suit in 90% of bodily injury claims, according to the reported figure. That does not predict any individual claim, but it shows why an initial response may not end negotiations.
A demand should distinguish established expenses from losses still being evaluated. If medical care continues, sending a package too early may leave future effects unclear. When the evidence is ready, a lawyer can make a supported demand, address the adjuster’s response, and negotiate. A consultation can help identify missing records and clarify what the package needs before submission to State Farm. Keep copies of submissions and responses so each next step reflects the claim record.
4. Settlement negotiation and mediation examples
Settlement negotiations address the gap between the insurer’s offer and the compensation supported by the claim. Your lawyer can compare the offer with medical evidence, lost income, damage records, and available coverage. If State Farm disputes fault or the value of an injury, a focused response should address the specific issue with supporting evidence.
Counteroffers can move discussions beyond an insurer’s first figure. The change shows why a documented response matters, but it does not establish a standard result for other claims.
Mediation offers another setting for negotiations. A mediator helps the parties discuss disputed issues, while the client decides whether to accept or reject proposed terms. The session can help the parties examine liability evidence, treatment records, and coverage.
Other Florida examples show how policy limits and multiple sources of coverage can shape a settlement. A scooter-collision insurer paid a $100,000 bodily-injury policy limit. In a separate Florida bodily-injury claim, the total settlement from the at-fault driver’s State Farm coverage and the client’s underinsured-motorist coverage was $125,000 in 2025. Identifying every potentially applicable policy can therefore change the negotiation picture.
A Florida motor-vehicle case reached $325,000 in bodily-injury settlement and other insurance payouts in 2023. These examples involve different facts and coverage arrangements. They illustrate why a settlement estimate must account for more than one policy when applicable.
Payment sources matter alongside injury and liability evidence. A negotiation should make each source of compensation clear rather than treating the total as one unexplained figure.
Before mediation, a lawyer can organize the claim’s strongest evidence, identify disputed points, and calculate a proposed resolution. During negotiations, compare each offer with documented losses and available coverage. A report, medical record, or policy document may answer a specific challenge. Before agreeing to resolve the claim, the client should understand the release terms and total payment.
5. What are the steps in State Farm’s car accident claims and settlement process?
A car accident claim generally begins with notice to the insurer and basic crash details. The claim file needs the collision date, location in Florida, involved drivers and vehicles, and reported injuries. A police report can help establish what happened and identify information that needs follow-up. The insurer then reviews the claim and may request records or forms. Clear, consistent details give that review a useful starting point.
Next, the claim handler evaluates available evidence and the types of coverage involved. For an auto accident injury claim, a customer may need to complete and submit Personal Injury Protection and/or Medical Payments Coverage forms. Florida PIP requires initial services and care within 14 days after a motor vehicle accident for specified medical benefits. That timing can matter when the insurer reviews those benefits.
Records help connect the crash to the claimed losses. The claim file may include the police report, vehicle-damage photographs, medical bills, policy information, and rental receipts. Photos document visible damage, bills show expenses, and rental receipts support transportation costs. An organized file also makes gaps or inconsistent dates easier to spot. The State Farm car accident settlement process depends on a clear claim record, not just an initial report.
During its review, an adjuster may ask about the crash, injuries, treatment, or expenses. Give accurate information, but keep answers focused on what was asked. Don’t speculate about fault or present uncertain details as facts. Don’t agree to a recorded statement or provide full medical records without understanding the request. The claim should include relevant information, not unrelated personal history.
After reviewing the evidence, the insurer may make an offer, request more documentation, or dispute part of the claim. Respond to the specific issue. If State Farm questions a rental expense, for example, the receipt and repair timeline can clarify its amount and purpose. If the insurer disputes how the collision happened, the report, photographs, and consistent accounts can help address liability. At this stage, the State Farm car accident settlement process may call for a precise, evidence-based response.
Negotiations continue until the parties resolve disputed value and terms, or the claim moves to another stage. An attorney can manage communications, organize records, and assess whether an offer accounts for documented losses and available coverage. The client can provide accurate documents and answer questions about treatment or daily effects. Add each update to the claim file so the next response reflects the current evidence.
Before accepting any resolution, review the written terms and any release. Confirm which claims the agreement addresses and what payment it resolves. If you need help organizing a Florida accident claim or evaluating insurer communications, contact the legal team about your claim.
Personal Injury Attorney in Fort Lauderdale
Personal Injury Attorney in Fort Lauderdale represents injured people in Fort Lauderdale and throughout Florida, including Miami, West Palm Beach, Boca Raton, Delray Beach, Boynton Beach, Lake Worth, Orlando, and Tampa. If State Farm questions fault, injury records, or coverage, legal representation can organize evidence, manage insurer communications, and explain settlement terms before you decide. The firm represents people injured in car, truck, and rideshare crashes, as well as pedestrians hurt while walking, jogging, or bicycling.
Consider legal help if an offer arrives before your treatment picture is clear, the insurer disputes responsibility, or multiple policies may apply. Support can also help keep the claim focused on documented losses rather than assumptions. To discuss your situation, contact Personal Injury Attorney in Fort Lauderdale.
Call Now: (954) 390-2228 Available 24 Hours a Day, 7 Days a Week
Move Forward With a Clear Plan
The next step is deciding whether the insurer’s position reflects the evidence and the recovery you need. A careful review of the State Farm car accident settlement process can help you identify unresolved questions before you make a final decision. If the claim feels difficult to manage, you don’t have to face the insurer alone. Personal Injury Attorney in Fort Lauderdale represents people injured in car, truck, and rideshare accidents, helping them address insurance disputes and pursue accountability. The right approach depends on the facts of your situation, including the injuries and available evidence.
Choose a path that protects your ability to make an informed decision. Contact Personal Injury Attorney in Fort Lauderdale to discuss your accident claim and the support you may need. A clear next step can make a demanding process easier to face.
Call Now: (954) 390-2228 Available 24 Hours a Day, 7 Days a Week
Frequently Asked Questions
Are There Any Limits to My Amount of Recovery?
Yes. The amount available may be limited by applicable insurance coverage, losses supported by evidence, and Florida’s comparative-fault rules. A lawyer can review how those factors apply to a particular claim. For example, available policy coverage may affect what an insurer can pay, while evidence of responsibility and documented losses shape the claim’s value.
What Compensation Can I Recover?
Recoverable compensation may include medical expenses, lost income, pain and suffering, emotional distress, property damage, and effects on future earning capacity. Which categories apply depends on the crash and the evidence. A lawyer can assess whether records support each claimed loss. Repair documentation, for example, may support a property-damage claim, while employment records can help show income lost during recovery.
How can an injury lawyer respond if State Farm’s settlement offer is too low?
An injury lawyer near me or a personal injury lawyer near me can identify what the offer leaves unresolved, then present relevant evidence and a reasoned counterproposal. A personal injury firm near me can review the offer’s terms, while attorneys for personal injuries can address disputed losses or liability. Lawyers for auto accidents can also explain how documented treatment relates to the collision.
How can attorneys negotiate a State Farm car accident settlement on a client’s behalf?
Attorneys can manage communications, organize the claim’s supporting evidence, and explain why the requested compensation fits the documented losses. The phrase “attorneys personal injury” refers to counsel handling injury claims, while auto accident lawyers near me describes legal help for crash-related matters. The client remains involved in settlement decisions, including whether proposed terms resolve the claim. This information is general and isn’t legal advice.
What deadlines and statutes of limitations apply to State Farm accident claims in each state?
The 20-day deadline applies to payment after a written Florida settlement, not to filing a lawsuit. Any lawsuit filing deadline must be assessed under Florida law for the particular claim; the information here does not cover other states.
Disclaimer
The information provided on this blog is for general informational purposes only and does not constitute legal advice. Viewing this content does not create an attorney-client relationship with the firm. You should not act or rely on any information contained herein without seeking legal advice from a qualified attorney regarding your individual situation.